The Sublease Market Nobody Maps
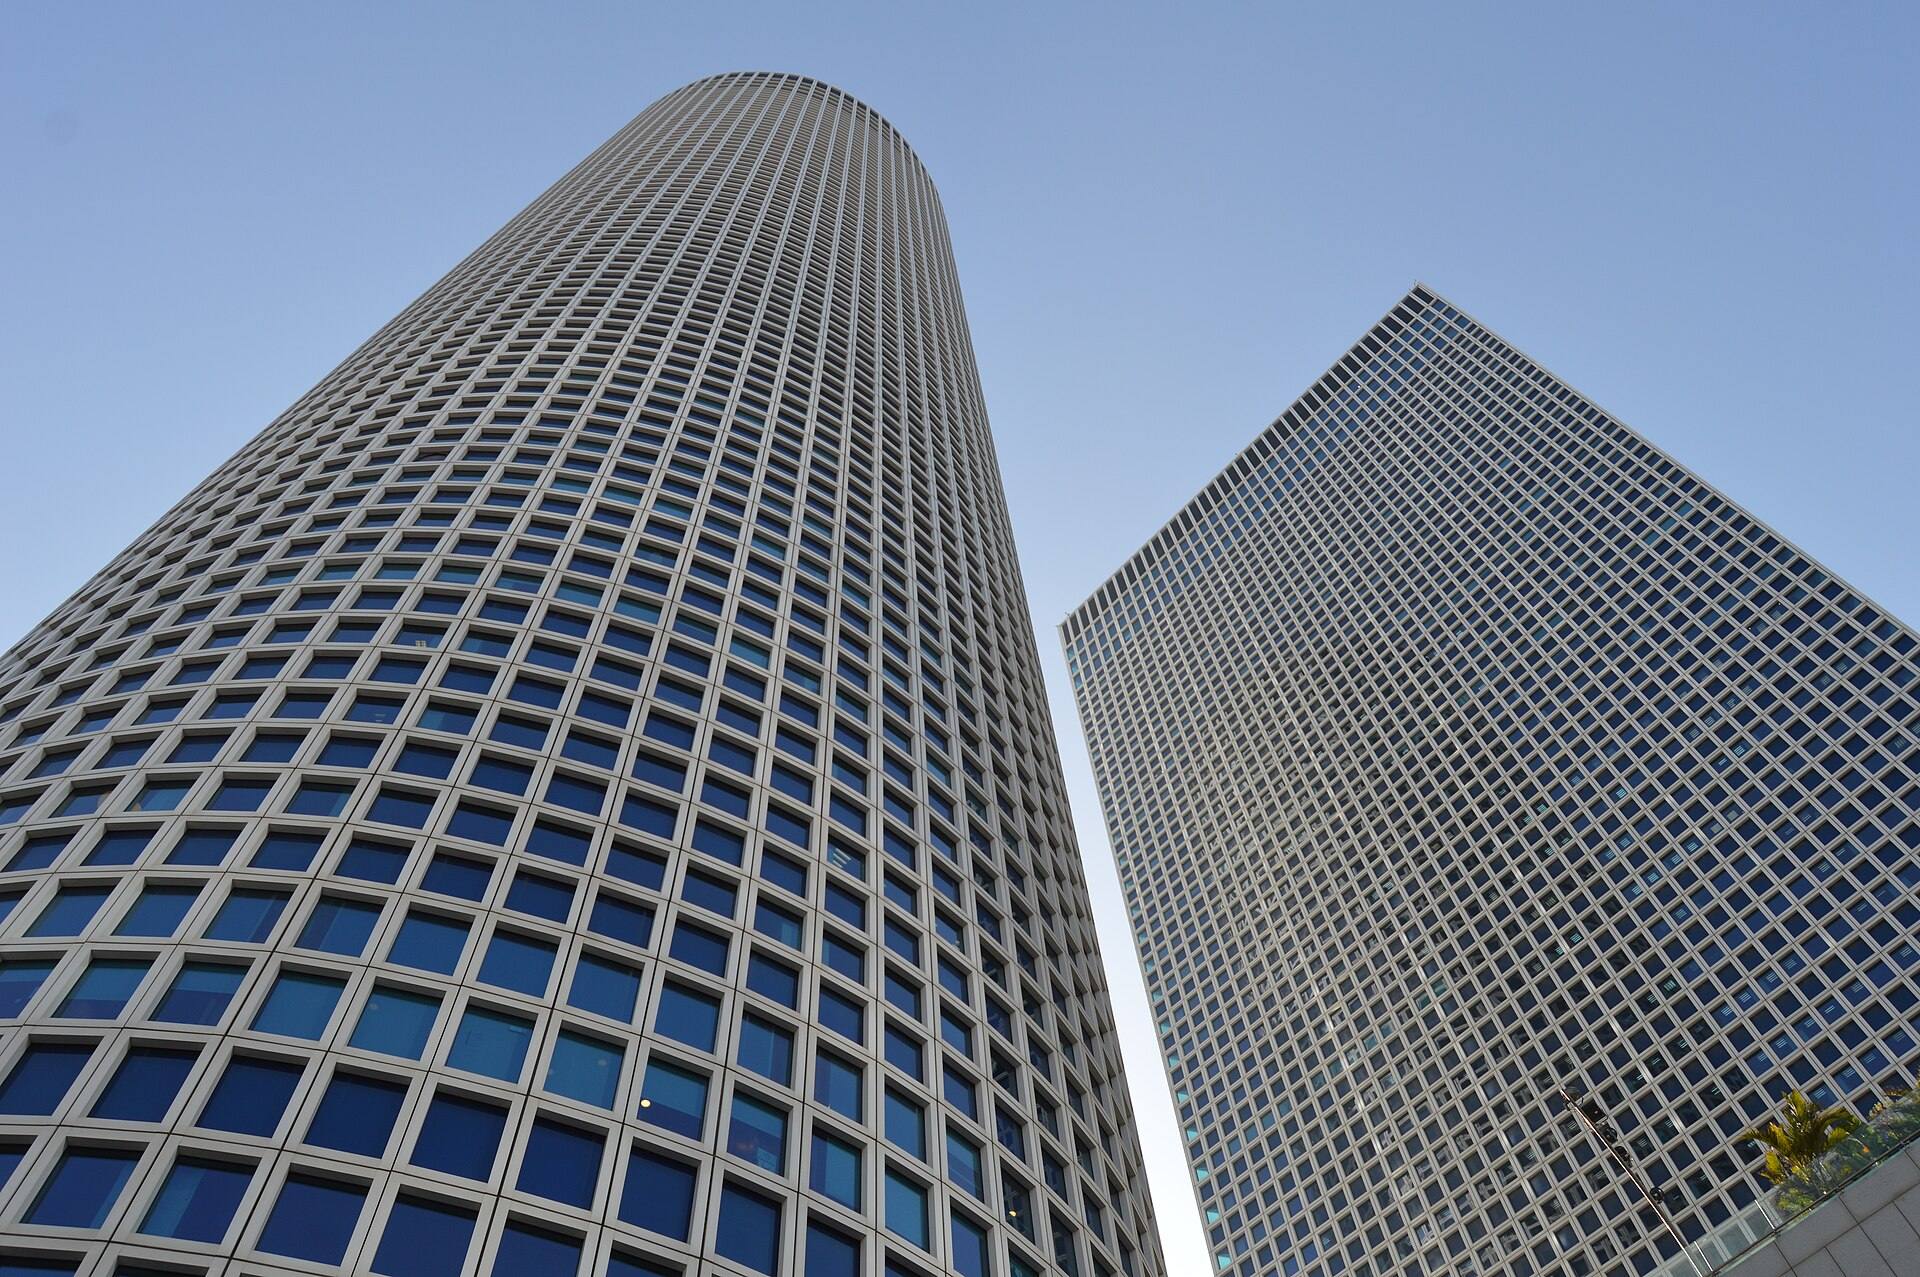
The Azrieli Center towers, Tel Aviv
Every quarter, a number of Tel Aviv companies quietly conclude they are holding more office space than they need. A hiring plan was revised. A team consolidated. A second floor taken in optimism now sits half-used.
That space does not disappear. It re-enters the market as sublease inventory, and it moves through a channel that almost nobody maps, prices inconsistently, and most tenants never see.
Why sublease inventory is invisible
Direct vacancy is public. A landlord with an empty floor wants the market to know: the floor is listed, marketed, and priced against comparable stock.
A company subleasing excess space wants close to the opposite. Announcing that you are shedding a floor is a signal about your business, and it is read that way, by employees, by candidates, sometimes by investors. So the space is offered discreetly, through brokers and personal networks, and frequently without any listing at all.
The result is a shadow layer of availability that never appears in a vacancy statistic. In a market like Tel Aviv's core corridors, where the count of large contiguous floor plates is small enough to hold in your head and occupancy reached 99% in the first half of 2026 according to a Newmark Natam survey reported by Globes, that shadow layer is not a rounding error. It is often the only genuinely negotiable inventory in the building.
Time, not price, is the governing variable
A landlord with an empty floor is patient. The floor is an asset held for decades; a quarter of vacancy is an accounting event, not a crisis.
A company subleasing is the opposite. It is paying rent on space it does not use, every month, against a lease that may run for years. Each month without a sublessee is a permanent loss with no recovery mechanism.
This asymmetry is the whole market. Two parties are offering comparable space in the same building, and one of them is watching a clock. Sublease pricing therefore tends to soften along a curve, not because the space is worse, but because the holder's position weakens with every month that passes. Globes reported in August 2025 that sublets are often priced below direct leases, sometimes by as much as 20%.
Which produces an uncomfortable truth for anyone shedding space: the discount you refuse in month one is usually smaller than the discount you accept in month seven, plus six months of rent you paid in between.
What the sublessee is actually buying
A sublease is not a lease. The distinction matters more than most tenants realise before signing.
You are taking an interest that sits underneath somebody else's obligation. If the original tenant defaults on the head lease, your position is exposed regardless of whether you have paid every shekel on time. Your term cannot outlast theirs. Any option to renew usually belongs to them, not to you, and frequently cannot be assigned.
Against that, the sublessee typically receives space that is already built. Fitted, cabled, furnished, occupancy-ready, delivered at a fraction of what the same build-out would cost from shell-and-core, and available in weeks rather than the many months a fit-out programme requires.
For a company that needs to be operational quickly, that combination is often decisive. But it should be a decision, not a surprise, and the head-lease terms belong on the table before the space is toured, not after.
For companies holding excess space
Three things are worth knowing before you begin.
Under Israeli law, subletting requires your landlord's consent, given in advance and in writing, although a landlord may not refuse on unreasonable grounds (section 22 of the Tenancy and Borrowing Law, 1971). Many leases add restrictions of their own, and some prohibit subleasing outright. Read that clause before you market anything.
This is general information, not legal advice: review your lease with an Israeli real-estate lawyer before subletting.
Your own lease terms set the ceiling on what you can offer. A sublessee cannot be given more than you hold: not more term, not more expansion right, not more flexibility.
And the space competes directly with the landlord's own vacancy in the same building, against a counterparty with a longer horizon and a stronger balance sheet. That is a difficult competition to win on price alone. It is usually won on speed and on condition, on being the option that is ready now.
The practical conclusion
Sublease inventory is the least legible part of the Tel Aviv office market and, in many quarters, the part where the actual negotiating room sits.
For tenants, it is worth asking about explicitly, because it will not appear on any list you are shown. For companies holding space they no longer need, the cost of waiting is not theoretical. It is a rent payment, repeated monthly, while the position weakens.
Either way, the space is out there. It simply does not announce itself.
Sources
- Globes: Israeli tech firms sublet office space to cut costs (August 2025)
- Calcalist: After the big eyes, tech companies are forced to take in subtenants (January 2023, Hebrew)
- Globes: Defense-tech boom pushes up Tel Aviv office rents (September 2026)
- Tenancy and Borrowing Law, 5731-1971, section 22 (Hebrew text, Wikisource)