Opinion: The “Family Office” Effect on Tel Aviv Commercial Real Estate
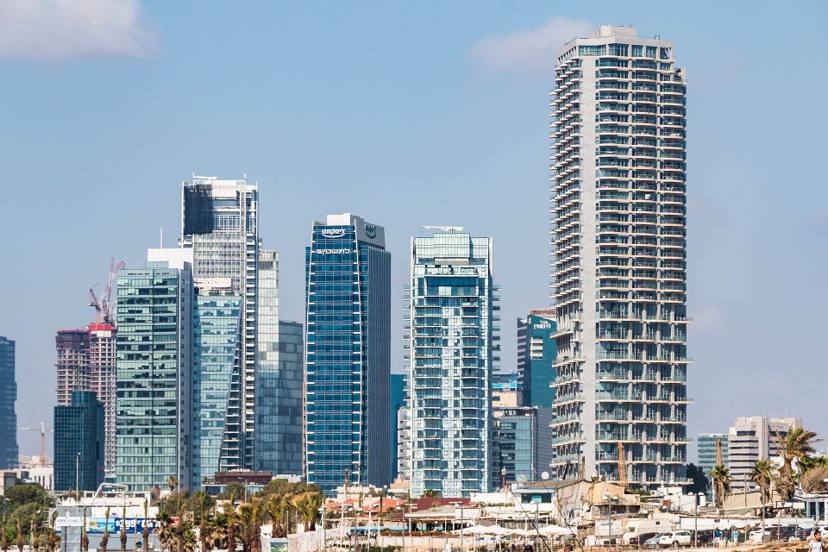
The Museum Tower, Berkowitz Street, Tel Aviv
Opinion. By Tamir Oudi, Founder, Bauhouse. This column is his reading of the market, not a research report; the figures in it come from the sources listed at the end.
In my reading of the market, private wealth managed by family offices is set to become a more visible force in Tel Aviv's commercial real estate, reinforcing a shift from speculative, high-leverage development toward long-term capital preservation. No published data series tracks family office purchases in Tel Aviv, so this is a view, not a statistic.
What the data does show is the environment such buyers would be stepping into: prime Class-A office towers that are almost full, financing that became far more expensive in 2022 and 2023, and family offices worldwide turning back toward real estate. My argument is that prime Class-A office space and premium retail in the city's central business districts (CBD), notably along the Rothschild Boulevard corridor and around Sarona, suit buyers who put generational wealth preservation ahead of short-term exits, and that such buyers can help stabilize prime values and support demand for sustainable "green" buildings.
Key Facts
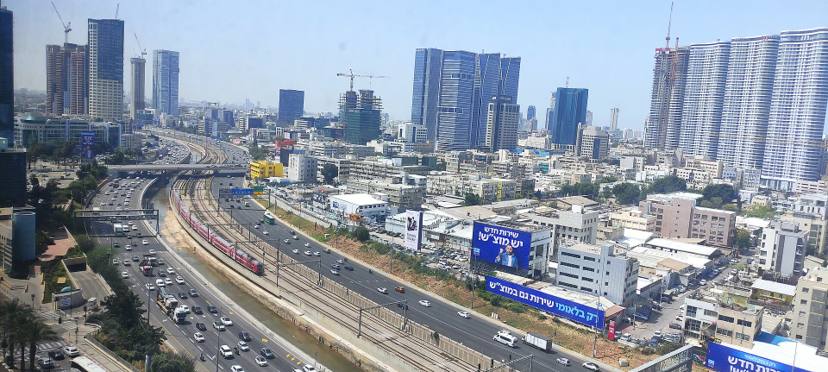
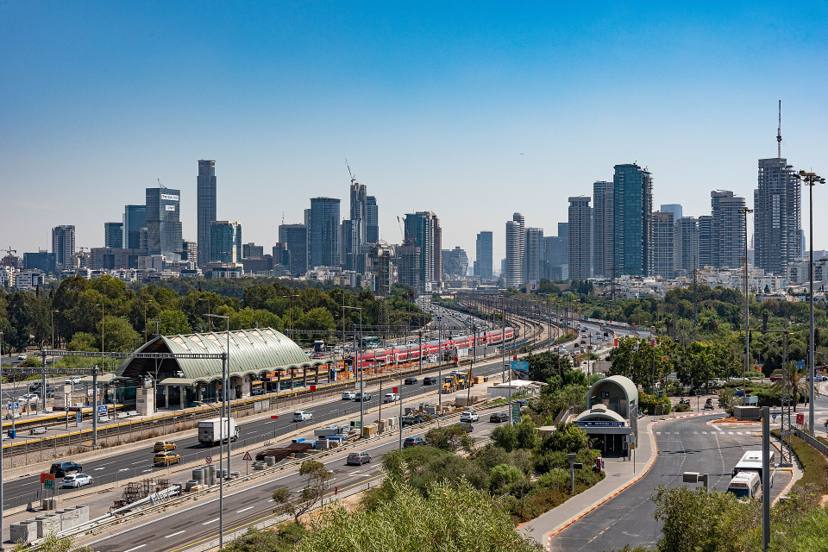
- Prime Class-A office towers in Tel Aviv command the city's highest rents: about ₪151 per square meter per month on Menachem Begin Road (the axis that includes Sarona) and ₪139 on Yigal Alon in H1 2026, according to Newmark Natam data reported by Globes.
- Occupancy in those prime areas reached 99% in H1 2026. Older Class-B buildings, which lost tenants to newer towers in 2025 (their occupancy fell from 93.25% to 87.41% in H2 2025), recovered to 91.37% in H1 2026.
- Globally, PwC's Global Family Office Deals Study (April 2025) reports that real estate is regaining prominence in family office deal-making, with investors drawn by income growth and long-term value.
- Financing became far more expensive after the Bank of Israel raised its policy rate ten times between April 2022 and May 2023, to 4.75%, a shift that favors buyers who need little or no debt.
The Strategic Shift: Generational Capital vs. Institutional Mandates
If family offices do become a larger force in Tel Aviv commercial real estate, as I expect, it will mark a structural shift in how prime assets are capitalized. In my experience, the city's commercial market has historically been led by public real estate companies, institutional investors such as insurers, and highly leveraged developers. The rise in interest rates since 2022 has changed the math for institutional players who rely heavily on debt to reach their target internal rates of return (IRR).
Family offices, by contrast, typically operate under a different set of mandates. Managing the personal fortunes of ultra-high-net-worth (UHNW) families, they generally prioritize wealth preservation, inflation hedging, and generational transfer over immediate, double-digit annual returns. They also tend to hold assets longer than private equity funds, which work to fixed exit cycles.
The Luxury of Patience in a High-Interest Environment
Because family offices often invest discretionary capital, they are well positioned to buy with low leverage or entirely in cash. Where an institutional fund may need substantial borrowing to make an acquisition viable, a family office can often buy a prime asset with modest debt or none at all. In my view, that independence from expensive debt lets them move quickly on complex deals and accept initial yields that leveraged buyers find hard to justify.
Targeting the Rothschild-Sarona Axis
I expect this capital to concentrate in Tel Aviv's most defensive micro-locations rather than in secondary or tertiary markets offering higher nominal yields: Rothschild Boulevard, the area around Sarona, and the premium commercial high-rises of the city's core. These locations house multinational technology firms, leading financial institutions, and top-tier legal practices, and the occupancy figures (about 99% on the main axes in H1 2026) support the case for reliable, long-term rental income.
The Flight to Quality and Sustainable Class-A Assets
One marker I would watch for is demand for premium, sustainably built commercial properties. An investor who intends to hold an asset for decades has every reason to worry about structural and environmental obsolescence: a building that falls behind modern environmental standards today risks a "brown discount" in tomorrow's leasing market. The office data already shows a split between new and old stock. According to Newmark Natam, Class-B occupancy in Tel Aviv fell from 93.25% to 87.41% in H2 2025, and average rents in the older City/Rothschild area slipped from ₪136 to ₪130 per sqm, while rents on the newer Begin axis kept rising. Class-B occupancy has since recovered to 91.37% in H1 2026, but average Class-B rents stayed flat at about ₪86 per sqm, against ₪151 on the Begin axis.
The Premium on LEED and ESG Compliance
For that reason I expect family offices to favor buildings with advanced LEED certification, modern HVAC systems, and smart-energy infrastructure. Blue-chip corporate tenants, particularly the multinational tech companies operating in Tel Aviv, are often bound by global corporate social responsibility (CSR) commitments. In my view, owning ESG-compliant Class-A buildings is the surest way for a long-term holder to stay attractive to the highest-paying, most stable tenants.
High-Street Retail and Mixed-Use Integration
Beyond office towers, I see a natural fit between family office capital and boutique high-street retail at the base of luxury residential and commercial developments in areas like Neve Tzedek and Jaffa. Commercial leases in Israel are commonly linked to the Consumer Price Index (CPI), and retail leases sometimes include turnover clauses, which can give owners a degree of inflation protection and a share in rising consumer spending in the city's most affluent neighborhoods.
Market Stabilization and the New Valuation Floor
Tel Aviv has not been immune to downturns: average Class-A office rents fell about 11%, from ₪146 to ₪130 per sqm, between H1 2022 and H1 2023, according to Newmark Natam data reported by Globes. My argument is that patient private capital can act as a shock absorber in such periods: when institutional buyers step back to preserve liquidity, a family office with a multi-decade horizon can treat the pause as a buying opportunity.
My own view is that family offices are unlikely to judge Tel Aviv through a five-year macroeconomic lens. For a long-term holder, the city's standing as a global technology and cultural hub matters more than the current cycle, and market corrections look like entry points rather than warnings.
If that is right, this long-term perspective helps support values for prime properties: sellers of Class-A assets in the CBD can count on a pool of private, liquid capital ready to consider premium properties at fair valuations, even when institutional demand softens. The current data is at least consistent with a recovery: with occupancy in the main office axes back at 99% in H1 2026, prime Tel Aviv offices have regained their footing.
Frequently Asked Questions
Why might family offices prefer Tel Aviv commercial real estate to residential assets?
In my view, premium residential real estate in neighborhoods like the Old North and Neve Tzedek remains highly attractive, but commercial Class-A assets offer family offices greater scale, predictable cash flow from long corporate leases, and professional tenant management. Commercial assets also allow more capital to be deployed in a single transaction, which lightens the administrative load on private wealth managers.
Where in Tel Aviv would family office commercial investment concentrate?
I would expect it to center on the central business districts: the Rothschild Boulevard corridor, the area around Sarona, and the premium office towers along the Menachem Begin and Yigal Alon axes, where occupancy reached about 99% in H1 2026. For boutique retail and mixed-use commercial assets, historic preservation projects in Neve Tzedek and Jaffa are the natural candidates.
How do family offices typically structure real estate acquisitions in Israel?
Practice varies, and there is no public data on it. In my experience, family offices tend to use conservative capital structures, often buying in cash or with low leverage, and many hold assets through a dedicated local company. Before buying, it is worth taking Israeli tax and legal advice on the structure.
Sources
- Globes: Defense-tech boom pushes up Tel Aviv office rents (September 2026)
- Merkaz HaNadlan: 2025 Tel Aviv office market summary, Newmark Natam data (April 2026)
- Merkaz HaNadlan: The light rail redraws the office map, from Newmark Natam's H1 2026 review (September 2026)
- Globes: Tel Aviv office rents fall sharply (September 2023)
- Globes: Bank of Israel hikes rate 0.25% again (May 2023)
- WealthBriefing: Family Offices Must Gear Up For Larger Investment Deals, PwC Study (April 2025)